Comparative Evaluation of Machine Learning Methods for Financial Market Volatility Classification
DOI:
https://doi.org/10.67119/s8c4mc88Keywords:
Machine Learning, Financial Markets, Volatility Prediction, Classification, Ensemble Learning, Investment Deci- sion SupportAbstract
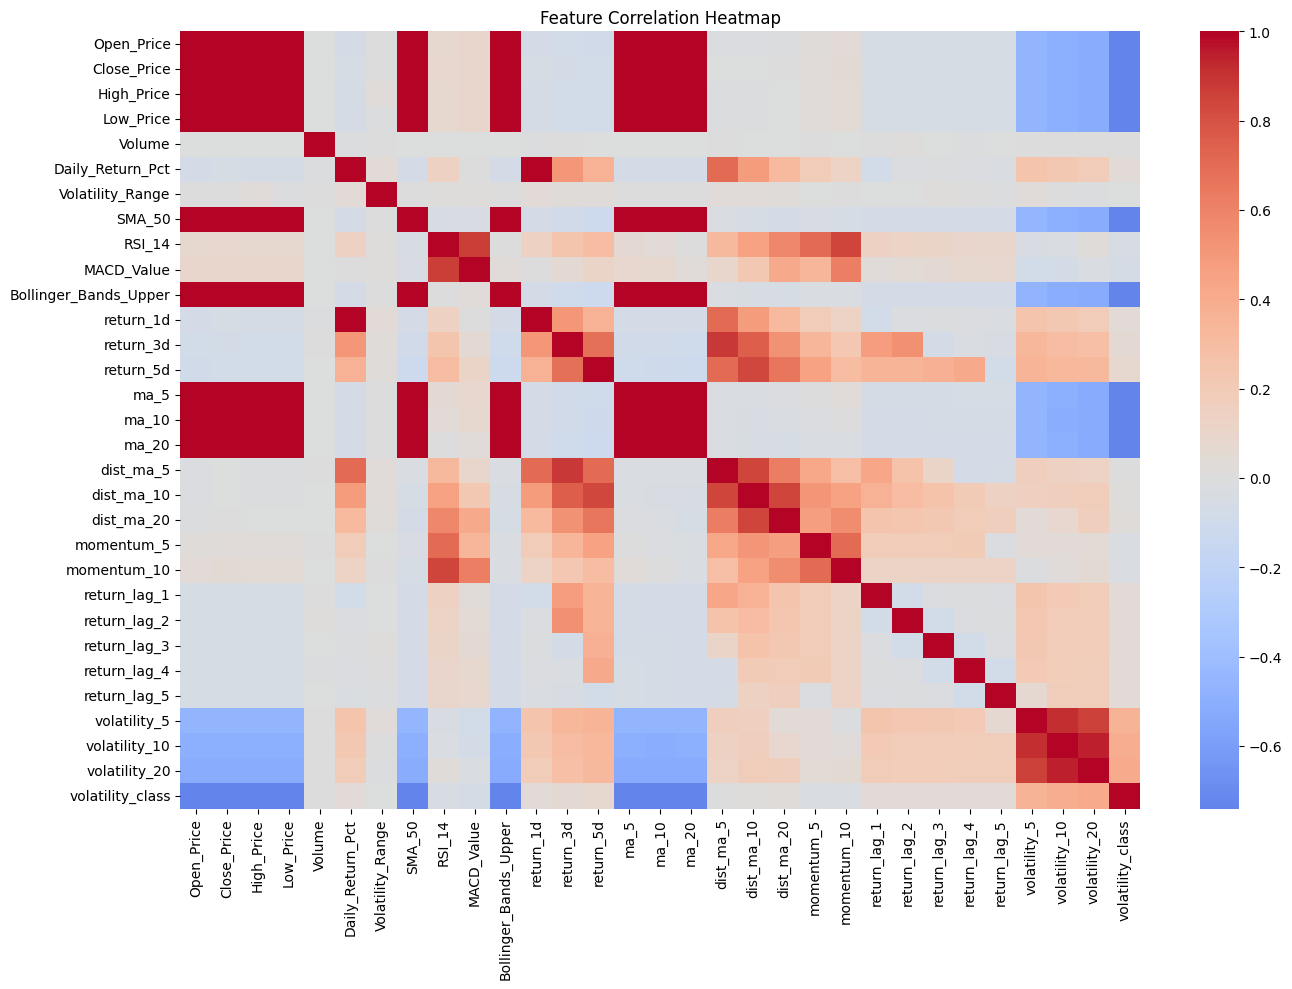
Financial market forecasting remains difficult because asset prices are strongly affected by randomness, noise, and limited short-term predictive information. Methods that aim to estimate precise future returns therefore often struggle to achieve consistently reliable results. To address this issue, this study reformulates the prediction task as a classification problem that distinguishes between different levels of market volatility, taking advantage of the persistence and clustering commonly observed in volatility dynamics. Ten machine learning methods are evaluated under a unified experimental framework, covering linear classifiers, support vector machines, instance-based approaches, decision trees, and ensemble techniques. The empirical results show that all tested models achieve classification accuracies above 80\%, indicating that future volatility states can be identified with relatively consistent performance across different model families. These findings suggest that volatility classification provides a comparatively stable and practically useful machine learning formulation for supporting financial decision-making.
Downloads
Downloads
Published
License
Copyright (c) 2026 All authors. All rights reserved.

This work is licensed under a Creative Commons Attribution 4.0 International License.